Author: admin

  • Off Grid Self Sustainable Home for Sale – Priest River Idaho
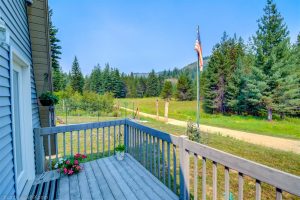
    Off Grid Self Sustainable Home for Sale –

    Priest River Idaho

    Off Grid Self Sustainable Home for Sale


    Looking for quiet, peaceful home on acreage and still close to town?  This Priest River Idaho home has what you are searching for plus the added bonus of being an off grid self sustainable home for sale on 10 acres.
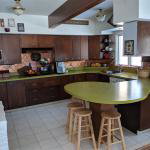
    Off Grid Self Sustainable Home for SaleWood accented chalet style open living area, with free standing wood stove comprises the focal point of this charming home.  Windows and door to the front porch and views of the mountains beyond.  Kitchen peninsula, with bar stool seating, separate the two areas.
    off grid self sustainable home for saleMain floor living with living room, dining area, kitchen, master bedroom with walk in closet, and master bath with garden tub, along with utility room all on main floor.  Step upstairs to the 2nd bedroom, which can easily be turned in the 2nd and 3rd bedrooms.  Plus a separate reading area or office upstairs.
    off grid self sustainable home for saleKitchen does not feel ‘Off Grid’.  Current owners have large fridge and newer gas burner over/range along with a dishwasher.  Large walk in pantry.  Open beams and window over the sink adding to the already wonderful ambiance.

    Master bath gives the choice of a garden tub soak or shower.  Walk in closet along and master bedroom all grouped together.  Both morning and evening light grace the bedroom with plenty of windows all around.
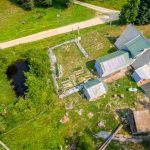
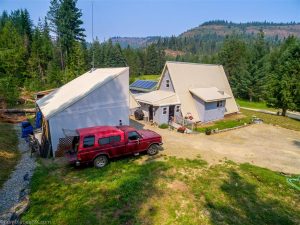
    off grid self sustainable home for salePlenty of outbuildings with a wood working shop a short distance from the covered rear porch main entrance.  Storage above the shop area makes this perfect for hobbies, crafts or maybe something else you have in mind. Free standing wood stove makes for plenty of heat no matter the weather outside.  Garden shed and wood shed close by as well.

    A deep natural pond sits adjacent to the fenced garden area.  Both in ground planting and raised garden boxes inside the fenced area.

    The list goes on of special items to be found with this off grid self sustainable home for sale.  One must see to appreciate all it has to offer.
    off grid self sustainable home for sale

    Experience the Difference Living In North Idaho will make.  Contact me as your local North Idaho Real Estate resource.

    Selkirk MLS #20182994   –   $268,000.00
  • How Much Is My Home Worth in Sandpoint, Idaho

    How Much is your home worth in Sandpoint, Idaho?  If you are planning on selling your home, that is a question you need answered.  As your Local Sandpoint Real Estate Expert, I can help you to learn the answer to that question.  I will personally do the research on your behalf and provide you with a detailed Free Market Analysis.  Please feel free to take a few moments to complete the basic information below and I will go straight to work for you.  Or, if you prefer, please feel free to give me a call directly at 208-255-6227.

    See: Homes for Sale in Sandpoint, Idaho

    FOR A COMPLETE MARKET ANALYSIS FORM: CLICK HERE (link to Free Market Analysis)
    IMAGE OF A HOME

  • Have You Ever Considered Purchasing a Home in Sandpoint, Idaho

    Have you ever considered moving to beautiful Sandpoint, Idaho?  Sandpoint is a desirable community & great location.  Sandpoint, Idaho boasts a variety of local landmarks, excellent schools, parks and much much more.  Take a look at some of the most popular searches in Sandpoint, Idaho and the surrounding areas.

    See: Homes for Sale in Sandpoint, Idaho

    Not quite the location that you are looking for?  That is okay.  Through my website you can search for the exact home you are looking for in the exact city, county or community you are looking for.  Search for your perfect home, in the perfect location by taking advantage of my Advanced Search tool built directly into this website.

  • Find Your Dream Home in Sandpoint, Idaho

    There are so many different kinds of homes out there for families to choose from.  Do I want to live in Sandpoint?  Or maybe you want to find a home in Sandpoint.  How many bedrooms and bathrooms do you need?  Do you need a large back yard?  A small backyard?  Do I even need, or want, a yard at all?  Don’t even get me started on the front yard and curb appeal.  Hardwood floors, tile, carpet.  There are so many things to consider when looking for your dream home.  How, then, do you find the right home for you?

    The answer is to put me to work for you.  That is what I do for my clients.  Completing my basic Dream Home Finder I can immediately go to work for you.  Of course you can take advantage of my Quick Search and my Advanced Search tools to surf through all the homes for sale in Sandpoint, Idaho or the surrounding areas.  By completing the Dream Home Finder, I can use additional resources at my disposal to locate homes for sale that may not be available in the public view.  In addition you are a busy individual and my passion is to work for you to find that dream home and schedule tours for you.  By working together as a team with your dreams and my resources, finding that dream home is only one tour away.  It is my passion to find you that one right tour.

  • North Idaho and Sandpoint ‘Ice Dams’

    Sandpoint ‘Ice dams’ are not specific to Sandpoint Idaho and surrounding North Idaho areas. Any cold weather states susceptible. The weather this season thus far has proven to be excellent for the forming of ‘ice damns’. While the name may sound cool, the damage that can be done to a home is not.
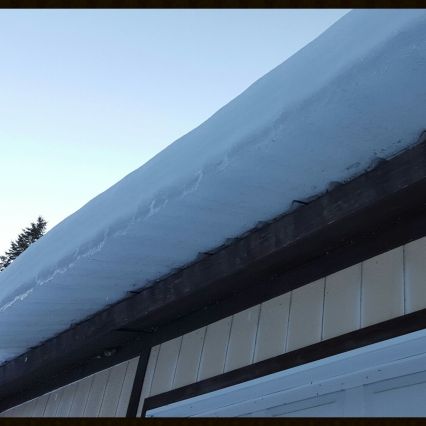
    Ice Dams are those formations of ice at the edge of roofs.  Yes those wonderful ice cycles we all enjoy looking at are tell tale signs of ice dams and possible damage, many times serious, secretly happening without our knowledge until too late.

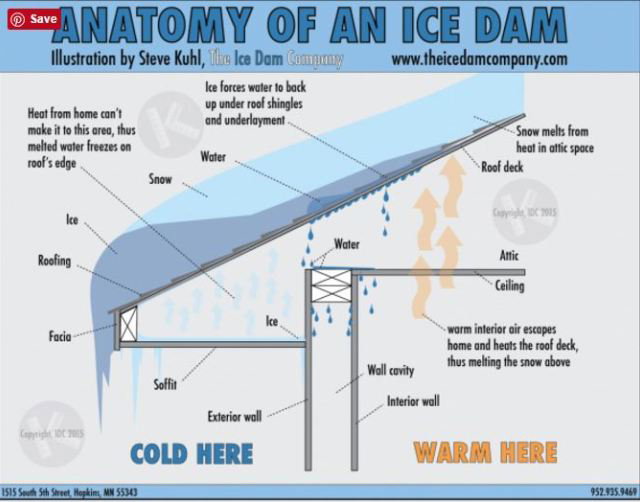
    For excellent information on ice damns and possible damage and tips for removal I suggest going to http://www.icedamcompany.com/about-ice-dams/ based out of Minnesota.  The diagram below, from the Ice Damn Company is excellent in showing exactly what is happening behind the ice we see.

    Sandpoint 'Ice Dams' no different

    illustration Courtesy Ice Damn Company – MN.

    So next time you are enjoying one of those Sandpoint ‘Ice Dams’,  realize the damage that may be lurking behind the beauty of a simple ice cycle !

  • Bonners Ferry Idaho Home for Sale – 4 bedroom 2 bath

    Lovely nostalgic in town Bonners Ferry Home for sale with end of road privacy.  This charming 4 bedroom, plus 5th non conforming, and 2 baths home has 1,822 sq. ft.,  and sits at end of the road on a double lot totaling .35 acres.  Close to all Bonners Ferry amenities, this is a home very much worth looking at.
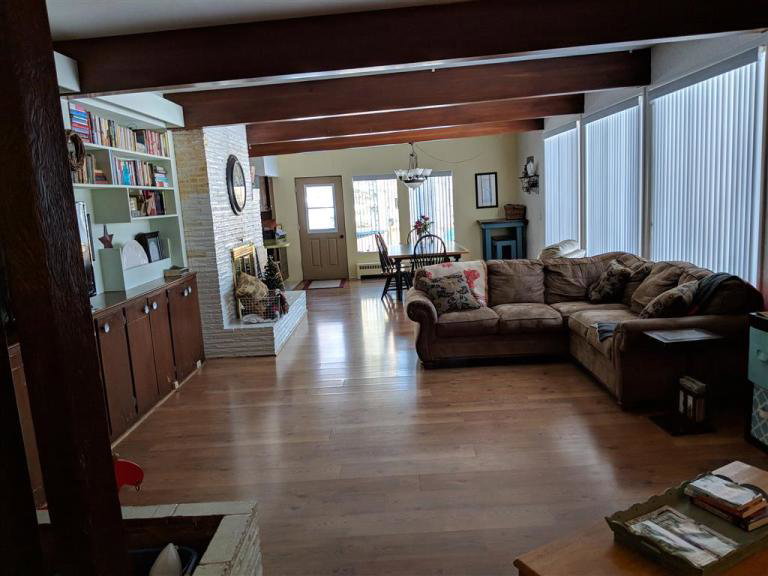
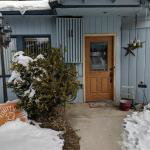
    Main floor living with kitchen opening to large dining and living room area.  Over sized windows bring the warmth of the day in with natural sunlight.  Master bedroom and 2 additional bedrooms on the main floor as well.  Step from the covered main entrance, off the 2 car carport, into hall way leading either to the kitchen or living room  Kitchen offers plenty of cupboard space and views to the large yard and tree house, along with filtered views to downtown Bonners Ferry.

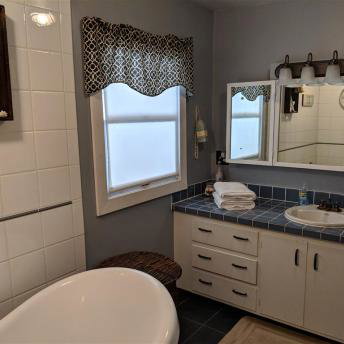
    Large 4th bedroom is on lower level along with a small shop / craft room plus a pantry – storage room.  Master bath has been redone with stand alone bath tub.  Very cute bathroom.  The attic offers the hideaway bonus room, with the possible 5th non conforming bedroom.
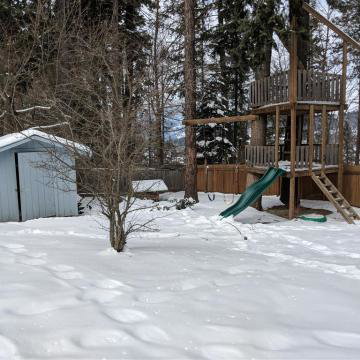
    The double lot allows for plenty of fenced outside room with a cool tree house.  There is a covered patio and open deck.

    This home includes an in ground pool although there is no value given with winter still upon us  and can not be sure of pump house condition.

    Experience the difference ‘Living In North Idaho’ will make.  Contact me as your local North Idaho Real Estate resource.

    6537 Jefferson – Bonners Ferry – Idaho 83805

    MLS 20180497

    $169,000.00

  • Your Savings and Down Payment

    Your First Step Toward Buying a Home

    When preparing to buy a home, the first thing many homebuyers do is look at the real estate ads in newspapers, magazines and listings on the Internet. Some potential buyers read how-to articles like this one. The next thing you should do – before you call on an ad, before you talk to a REALTOR®, before you shop for interest rates – is look at your savings.

    Why?

    Because determining how much money you have available for down payment and closing costs affects almost every aspect of buying a home – including how you write your purchase offer, the loan programs you qualify for, and shopping for interest rates.

    Mortgage Programs

    If you only have enough available for a minimum down payment, your choices of loan program will be limited to only a few types of mortgages. If someone is giving you a gift for all or part of the down payment, your options are also limited. If you have enough for the down payment, but need the lender or seller to cover all or part of your closing costs, this further limits your options. If you borrow all or a portion of the down payment from your 401K or retirement plan, different loan programs have different rules on how you qualify.

    Of course, if you have enough for a large down payment, then you have lots of choices.

    Your loan choices include such varied programs as conventional fixed rate loans, adjustable rate mortgages, buydowns, VA, FHA, graduated payment mortgages and all the varieties of each.

    Shopping for Rates

    A very important reason you need to have at least some idea of your down payment is for shopping for interest rates. Some loan programs charge a slightly higher interest rate for minimal down payments. Plus, the interest rates for different loan programs are not the same. For example, conventional, VA, and FHA all offer fixed rate loans. However, the rates vary from one program to another.

    If you shop lenders by phone, the loan officer will be able to tell you which programs fit and quote your rates accordingly. However, if you are shopping on the Internet, you have to develop some idea of your loan program on your own.

    Writing Your Offer

    Another reason you need to have a clue about your down payment is because it affects how you write your offer to purchase a home. Not only are you required to put your down payment information in the offer, but also different loan programs have different rules that also affect how you write your offer. This is especially important when dealing with FHA and VA loans.

    If you are asking the seller to pay all or part of your closing costs, you have to be certain your loan program allows what you are asking. For smaller down payments, lenders allow the seller to pay less closing costs than for larger down payments. Some loan programs will allow a seller to pay certain types of costs, but not others.

    Finally, your down payment also affects your ability to qualify for a loan. When you make a small down payment, lenders are fairly strict about having you conform to their underwriting guidelines. For larger down payments, they will tend to make allowances or exceptions to the rules.

    Conclusion

    As you can see, the down payment affects every choice you make when you buy a home. Although you should look at ads, familiarize yourself with neighborhoods, learn about prices, and read as much as you can – when you get ready to take action – the first thing you should do is figure out how much money you have available for the purchase.

  • Why You Should Not Make Any Major Credit Purchases

    Don’t go on a spending spree using credit if you are thinking about buying a home, or in the process of buying a new home. Your mortgage pre-approval is subject to a final evaluation of your financial situation.

    Every $100 you pay per month on a credit payment could cost you about $10,000 in home eligibility. For example, a car payment of $300/month could mean that you qualify for $30,000 less in a mortgage.

    Even if you have accumulated enough savings, you should consider not making any large purchases until after closing. The last thing you want is to know that you could have purchased a new home had you curbed the urge to spend.

  • Why Do You Need Title Insurance?

    Title Insurance.

    It’s a term we hear and see frequently – we see reference to it in the Sunday real estate section, in advertisements and in conversations with real estate brokers. If you’ve purchased a home before, you’re probably familiar with the benefits and procedures of title insurance. But if this is your first home, you may wonder, “Why do I need another insurance policy? It’s just one more bill to pay.”

    The answer is simple: The purchase of a home is most likely one of the most expensive and important purchases you will ever make. You, and your mortgage lender, want to make sure that the property is indeed yours – lock, stock and barrel – and that no individual or government entity has any right, lien, claim to your property.

    Title insurance companies are in business to make sure your rights and interests to the property are clear, that transfer of title takes place efficiently and correctly and that your interests as a homebuyer are protected to the maximum degree.

    Title insurance companies provide services to buyers, sellers, real estate developers, builders, mortgage lenders and others who have an interest in a real estate transfer. Title companies routinely issue two types of policies – “owner’s”, which cover you, the homebuyer; and “lender’s”, which covers the bank, savings and loan or other lending institution over the life of the loan. Both are issued at the time of purchase for a modest, one-time premium.

    Before issuing a policy, however, the title company performs an extensive search of relevant public records to determine if anyone other than you has an interest in the property. The search may be performed by title company personnel using either public records or more likely, information gathered, reorganized and indexed in the company’s title plant.

    With such a thorough examination of records, any title problems usually can be found and cleared up prior to your purchase of the property. Once a title policy is issued, if for some reason any claim which is covered under your title policy is ever filed against your property, the title company will pay the legal fee involved in defense of your rights, as well as any covered loss arising from a valid claim. That protection, which is in effect as long as you or your heirs own the property, is yours for a one-time premium paid at the time of purchase.

    The fact that title companies work to eliminate risks before they develop makes the title insurance decidedly different from other types of insurance you may have purchased. Most forms of insurance assume risks by providing financial protection through a pooling of risks for losses arising from an unforeseen event, say a fire, theft or accident. The purpose of title insurance, on the other hand, is to eliminate risks and prevent losses caused by defects in title that happened in the past. Risks are examined and mitigated before property changes hands.

    This risk elimination has benefits to both you, the homebuyer, and the title company: it minimizes the chances adverse claims might be raised, and by so doing reduces the number of claims that have to be defended or satisfied. This keeps costs down for the title company and your title premiums low.

    Buying a home is a big step emotionally and financially. With title insurance you are assured that any valid claim against your property will be borne by the title company, and that the odds of a claim being filed are slim indeed.

    Isn’t sleeping well at night, knowing your home is yours, reason enough for title insurance?

    Article by CLTA

  • What is a Short Sale Anyway?

    An increase in foreclosure rates will inevitably bring with it an increase in short sales. But what is a short sale?

    A short sale happens when you sell your house for less than your remaining mortgage balance, the proceeds of which go to the lender and in return the lender forgives the remaining balance. Selling your home as a short sale is one way to avoid foreclosure.

    As a general rule, lenders lose money when they foreclose on a property. Consequently, they would rather not have to foreclose if it can be avoided. A short sale represents an opportunity to cut their losses because a short sale usually allows them to recoup more of the cost of the loan than a foreclosure process would.

    However, don’t think that a short sale is an easy thing to accomplish. In order to get permission for a short sale, you must provide documentation showing a genuine financial hardship. And don’t think that the decision for accepting a short sale is solely in the hands of the lender. Sure the lender must first agree, but this is not the final word. If there is mortgage insurance involved, this company also gets input on the decision. If there is an investor backing the mortgage, they also get input as to whether to accept a short sale.

    The transaction process for a short sale can be rather cumbersome as well, whether you’re on the buying or selling side. Many short sales fail due to additional demands by the lender, such as requiring the broker to reduce his or her commission and/or that the seller signs a document requiring him or her to pay back the shortfall.

    If you’re on the selling side of a short sale, consider having your agent or other experienced professional negotiate with your lender for a better deal. And remember, if the lender does accept a short sale and forgives part of your debt, that is considered taxable income and you must declare it as such to the IRS.

Share with