Blog

  • Mello-Roos

    In purchasing your new home, your future monthly payments will be made up of principal, interest, real property taxes, and insurance. But what is the tax for the Community Facilities District, otherwise known as a Mello-Roos District? The Land Title Association (LTA) has answered some of the most commonly asked questions about the Mello-Roos Community Facilities Act.

    What is a Mello-Roos District?

    A Mello-Roos District is an area where a special tax is imposed on those real property owners within a Community Facilities District. This district has chosen to seek public financing through the sale of bonds for the purpose of financing certain public improvements and services. These services may include streets, water, sewage and drainage, electricity, infrastructure, schools, parks and police protection to newly developing areas. The tax you pay is used to make the payments of principal and interest on the bonds.

    Are the assessments included within the Proposition 13 tax limits?

    No. The passage of Proposition 13 in 1978 severely restricted local government in its ability to finance public capital facilities and services by increasing real property taxes. The “Mello-Roos Community Facilities Act of 1982” provided local government with an additional financing tool. The Proposition 13 tax limits are on the value of the real property, while Mello-Roos taxes are equally and uniformly applied to all properties.

    What are my Mello-Roos taxes paying for?

    Your taxes may be paying for both services and facilities. The services may be financed only to the extent of new growth, and services include: Police protection, fire protection, ambulance and paramedic services, recreation program services, library services, the operation and maintenance of parks, parkways and open space, museums, cultural facilities, flood and storm protection, and services for the removal of any threatening hazardous substance. Facilities which may be financed under the Act include: Property with an estimated useful life of five years or longer, parks, recreation facilities, parkway facilities, open-space facilities, elementary and secondary school sites and structures, libraries, child care facilities, natural gas pipeline facilities, telephone lines, facilities to transmit and distribute electrical energy, cable television lines, and others.

    When do I pay these taxes?

    By purchasing an interest in a subdivision within a Community Facilities District you can expect to be assessed for a Mello-Roos tax which will typically be collected with your general property tax bill. These special tax payments are subject to the same penalties that apply to regular property taxes.

    How long does the tax stay in effect?

    The tax will stay in effect until the principal and interest on the bonds are paid off along with any reasonable administrative costs incurred in collecting the special tax or so long as it is needed to pay the expenses of services, but in no case shall exceed 40 years.

    What happens if a general tax payment is not made on time?

    Because the Mello-Roos tax is typically collected with your general property tax bill, the Facilities District that obtained the lien may withdraw the assessment from the tax roll and commence judicial foreclosure.

    What is the basis for the tax?

    Most special taxes levied on properties within these districts have been structured on the basis of density of development, square footage of construction, or flat acreage charges. The act, however, allows for considerable flexibility in the method of apportionment of taxes, and the local agencies may have established an entirely different method of levying the special tax against property in the district in question.

    How much will the Mello-Roos payment be?

    The amount of tax may vary from year-to-year, but may not exceed the maximum amount specified when the district was created. In the case of the purchase of a new house within a subdivision, the maximum amount of the tax will be specified in the public report. The Resolution of Formation must specify the rate, method of apportionment, and manner of collection of the special tax in sufficient detail to allow each landowner or resident within the proposed district to estimate the maximum amount that he or she will have to pay.

    How is the special tax reflected on the real property records?

    The special tax is a lien on your property, essentially like a regular tax lien. The lien is recorded as a “Notice of Special Tax Lien” which is a continuing lien to secure each levy of the special tax.

    How are Mello-Roos taxes affected when the property is sold?

    The Mello-Roos tax is assessed against the land, but is not based upon the value of the property, therefore, the possible increased value of the property does not affect the amount of the tax when property is sold. The amount of the tax may not exceed the original maximum amount stated in the Resolution of Formation. Any delinquent payments must be satisfied before the sale of the real property since the unpaid amounts are a lien against the property.
  • Mechanic’s Liens

    property lien

    The Mechanics’ Lien law provides special protection to contractors, subcontractors, laborers and suppliers who furnish labor or materials to repair, remodel or build your home.

    If any of these people are not paid for the services or materials they have provided, your home may be subject to a mechanics’ lien and eventual sale in a legal proceeding to enforce the lien. This result can occur even when the homeowner has made full payment for the work of improvement.

    The mechanics’ lien is a right that a state gives to workers and suppliers to record a lien and ensure payment. This lien may be recorded where the property owner has paid the contractor in full and the contractor then fails to pay the subcontractors, suppliers, or laborers. Thus, in the worst case, a homeowner may actually end up paying twice for the same work.

    The theory is that the value of the property upon which the labor or materials have been bestowed has been increased by virtue of these efforts and the homeowner who has reaped this benefit is required in return to act as the ultimate guarantor of full payment to the persons responsible for this increase in value. In practice, a homeowner faced with a valid mechanics’ lien may be compelled to pay the lien claimant and then pursue conventional legal remedies against the contractor or subcontractor who initially failed to pay the lien claimant but who himself was paid by the homeowner. Another justification for this result relates to the relative financial strengths of the parties to a work of improvement. The law views the property owner as being in a better situation to absorb the financial setback occasioned by having to pay the amount of a valid mechanics’ lien, as opposed to a laborer or material man who is viewed as being less able to absorb the financial burdens occasioned by not being paid for services or materials provided in connection with a work of improvement.

    The best protection against these claims is for the homeowner to employ reputable firms with sufficient experience and capital and/or require completion and payment bonding of the construction work. The issuance of checks payable jointly to the contractor, material men and suppliers is another protective measure, as is the careful disbursement of funds in phases based upon the percentage of completion of the project at a given point in the construction process. The protection offered by mechanics’ lien releases can also be helpful.

    Even if a mechanics’ lien is recorded against your property you may be able to resolve the problem without further payment to the lien claimant. This possibility exists where the proper procedure for establishing the lien was not followed. While it is true that persons who have provided labor, services, or materials to a job site may record mechanics’ liens, each is required to strictly adhere to a well-established procedure in order to create a valid mechanics’ lien.

    Needless to say, this is one area of the law that is very complex, thus it may be worthwhile to consult an attorney if you become aware that a mechanics’ lien has been recorded against your property. In the event you discover that a lien has been recorded but no effort has been made to enforce the lien, a title company may decide to ignore the lien. However, be prepared to be presented with a positive plan to eliminate the title problems created by this type of lien. This may be accomplished by means of a recorded mechanics’ lien release from the person who created the lien, or other measures acceptable to the title company.

    As in all areas of the real estate field, the best advice is to investigate the quality, integrity, and business reputation of the firm with whom you are dealing. Once you are satisfied you are dealing with a reputable company and before you begin your construction project, discuss your concerns about possible mechanics’ lien problems and work out, in advance, a method of ensuring that they will not occur.

  • Making a Good First Impression

    If you want buyers to be interested in your home, you need to show it in its best light. A good first impression can influence a buyer both emotionally and visually, thus prompting them to make an offer. In addition, what the buyer first sees is what they think of when they consider the asking price.

    A bad first impression can dissuade a potential buyer. Don’t show your property until it’s all fixed up. You do not want to give buyers the chance to use the negative first impression they have as means of negotiation.

    Ask around for the opinions others have of your home. Real estate agents who see houses everyday can give solid advice on what needs to be done. Consider what architects or landscape designers have to say. What you need are objective opinions, and it’s sometimes hard to separate the personal and emotional ties you have for the home from the property itself.

    Typically, there are some general fix ups that need to be done both outside and on the inside. As a seller, you should consider the following:

    • Landscaping – Has the front yard been maintained? Are areas of the house visible to the street in good condition?
    • Cleaning or Redoing the driveway – Is your driveway cluttered with toys, tools, trash etc.?
    • Painting – Does both the exterior and the interior look like they have been well taken care of?
    • Carpeting – Does the carpet have stains? Or does the carpet look old and dirty?
  • Living Trusts

    living trust

    Estate planners often recommend Living Trusts as a viable option when contemplating the manner in which to hold title to real property. When a property is held in a Living Trust, title companies have particular requirements to facilitate the transaction. While not comprehensive, answers to many commonly asked questions are below. If you have questions that are not answered below, your title company representative may be able to assist you, however, one may wish to seek legal counsel.

    Who are the parties to a Trust?

    A Family Trust is a typical trust in which the Husband and Wife are the Trustees and their children are the Beneficiaries. Those who establish the trust and transfer their property into it are known as Trustors or Settlors. The settlors usually appoint themselves as Trustees and they are the primary beneficiaries during their lifetime. After their passing, their children and grandchildren usually become the primary beneficiaries if the trust is to survive, or the beneficiaries receive distributions directly from the trust if it is to close out.

    What is a Living Trust?

    Sometimes called an Inter-vivos Trust, the Living Trust is created during the lifetime of the Settlors (as opposed to being created by their Wills after death) and usually terminates after they die and the body of the Trust is distributed to their beneficiaries.

    Can a Trust hold title to Real Property?

    No, the Trustee holds the property on behalf of the Trust.

    Is a Trust the best way to hold my property?

    Only your attorney or accountant can answer that question. Some common reasons for holding property in a Trust are to minimize or postpone death taxes, to avoid a time consuming probate, and/or to shield property from attack by certain unsecured creditors.

    What taxes can I avoid by putting my property in trust?

    Married persons can usually exempt a significant part of their assets from taxation and may postpone taxes after the first of them to die passes. You should check with your attorney or accountant before taking any action.

    Can I homestead property that is held in a Trust?

    Yes, if the property otherwise qualifies.

    Can a Trustee borrow money against the property?

    A Trustee can take any action permitted by the terms of the Trust, and the typical Trust Agreement does give the Trustee the authority to borrow and encumber real property. However, not all lenders will lend on a property held in trust, so check with your lender first.

    Can someone else hold title for me “in trust?”

    Some people who do not wish their names to show as titleholders make private arrangements with a third party Trustee; however, such an arrangement may be illegal, and is always inadvisable because the Trustee of record is the only one who is empowered to convey, or borrow against, the property, and a Title Insurer cannot protect you from a Trustee who is not acting in accordance with your wishes despite the existence of a private agreement you have with the Trustee.

  • Lead Poisoning

    lead paint

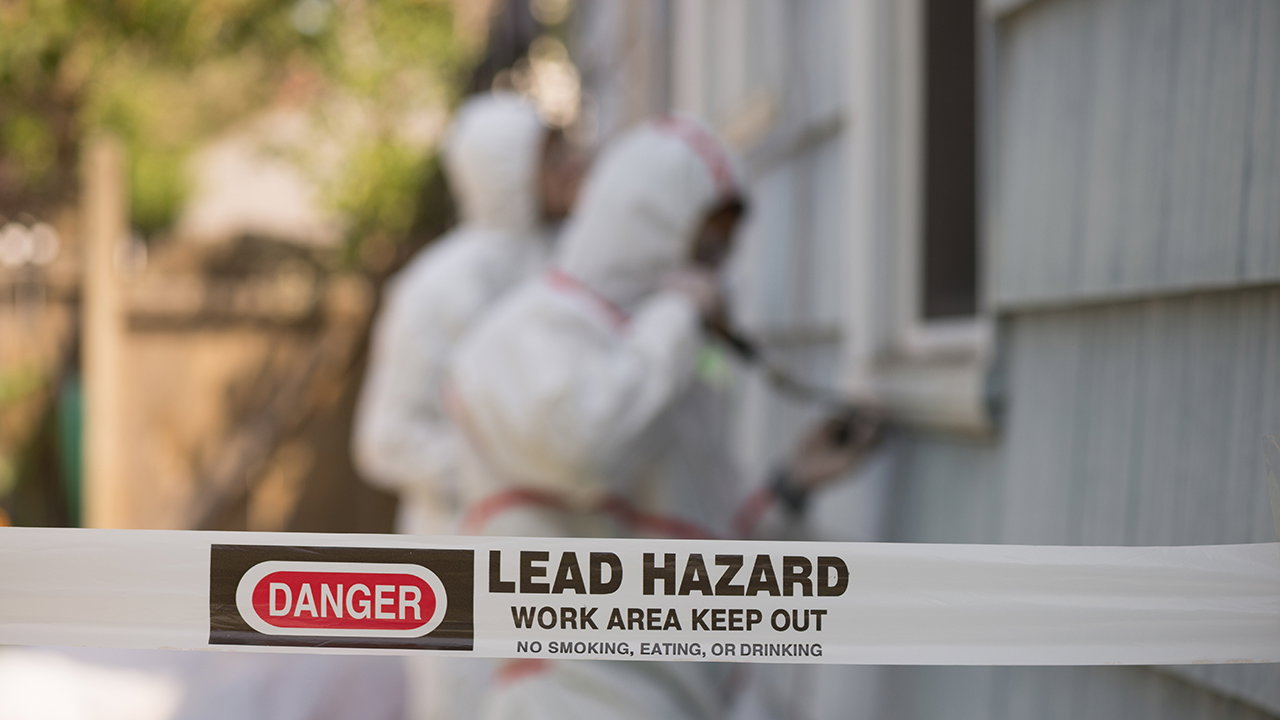
    Lead poisoning is a serious problem that can lead to adverse health problems. In children, high levels of lead can cause damage to the brain and nervous system, behavioral and learning problems, slow growth, and hearing problems. In adults, lead poisoning can cause reproductive problems, high blood pressure, digestive problems, nerve disorder, memory and concentration problems, and muscle and joint pain.

    Lead poisoning is especially a problem in cities with older buildings. Typically, lead is present in the paint from older buildings, in the water supply, and in the environment from cars and buses. Preventing lead poisoning in large cities, where there is such widespread possibility for exposure is both difficult and expensive. Federal programs have attempted to address this problem.

    Lead poisoning is also an issue that buyers and sellers need to consider. Houses that were built before 1978 probably have paint that contains lead. Federal law requires that sellers disclose known information on lead-based paint hazards before selling a house. Sales contracts must include a federal form about lead-based paint in the building. Buyers will have up to 10 days to check for lead hazards and are likely to stipulate corrections.

  • Land Contract

    An alternative to a non-conforming loan is the use of a land contract, which is allowed in some states. A land contract is an agreement between a buyer and a seller, where the buyer agrees to make periodic payments to the seller. The title to the property only transfers to the land contract buyer on fulfillment of the land contract obligations.

    A land contract can be helpful for those who need time to establish or improve their credit rating. There are only small closing costs, and payment can help establish a good mortgage payment record. This can help establish an overall good credit rating, and it is possible for the buyer to later refinance the land contract with a conforming loan.

    On the other hand, there are risks associated with land contracts. Land contract purchases are not necessarily recorded in the public record, and there are no guarantees that the seller will be able to transfer a clear title to the buyer upon fulfillment of the land contract. There also is no lender assuring that the purchase price for the property is justified, and no inspection of the property’s condition.

    Another alternative to a non-conforming loan is assuming the seller’s mortgage. By assuming a mortgage, if the mortgage is assumable, it is possible to save on closing costs, and may allow you to obtain a favorable interest rate.

  • Know Why You are Selling

    If you know exactly why you are selling then it is easier for you to follow the right plan of action for getting what you want.

    If you are a seller who needs to close a sale as quickly as possible, then you should know that getting the highest price possible is not one of your priorities. It does not mean that you won’t or cannot get the highest price, but it means that the price is not the deciding factor. A buyer who can give you a quick closing time will appeal much more to you than a buyer who can offer you more money but the negotiation and closing time drag on.

    It’s always good to know how low you will go in terms of selling price. This will help to eliminate some of the offers that you find simply offensive or ridiculous. Even though you should consider all offers seriously and take into consideration the terms of each offer, sometimes, if you know the bottom line and are strict about it, you can save yourself time.

    Once you know what your limits and reasons are, discuss them with your agent so that they can help you set your goals realistically. If you decide to list your home on your own, make sure you do research on the current market, and you get the proper advice you need in terms of legal issues, etc. The key is to be realistic and to know what your goals are so they can be met.

  • Items You Need When Applying For a Loan

    Have These Items Ready When You Apply For a Loan

    It used to be that lenders mailed out verifications to employers, banks, mortgage companies, and so on, in order to verify the data supplied by borrowers. Nowadays, the interest is often in speed and getting answers quickly so alternate documentation has become more widely used. Alternate documentation means that underwriting answers can be obtained with information supplied directly from the borrower instead of waiting around for verifications to come back in the mail.

    The following is required for most standardized loans as part of alternate documentation processing. Items may differ according to whether your loan is a conforming (Fannie Mae or Freddie Mac), non-conforming (jumbo) loan, government loan, or a portfolio loan.

    Verifications are still mailed out, but usually as part of quality control procedures.

    These are the things you need to supply to your lender to get a quick approval using alternate documentation

    Income Items

    • W2 forms for the last two years
    • Pay stubs covering a 30 day period
    • Federal tax returns (1040s) for the last two years, if:
      • you are self-employed
      • earn more than 25% of your income from commissions or bonuses
      • own rental property
      • or are in a career where you are likely to take non-reimbursed business expenses
    • Year-to-Date Profit and Loss Statement (for self employed)
    • Corporate or partnership tax returns (if applicable)
    • Pension Award letter (for retired individuals)
    • Social Security Award letters (for those on Social Security)

    Asset Items

    • Bank statements for previous two months (sometimes three) on all accounts. All pages.
    • Statements for two months on all stocks, mutual funds, bonds, etc.
    • Copy of most recent 401K statement (or other retirement assets)
    • Explanations for any large deposits and source of those funds
    • Copy of HUD1 Settlement Statement on recent sales of homes
    • Copy of Estimated HUD1 Settlement Statement if a previous home is for sale, but not yet closed
    • Gift letter (if some of the funds come as a gift from a family member)
    • Gifts can also require:
      • Verification of donor’s ability to make the gift (bank statement)
      • Copy of the check used to make the gift
      • Copy of the deposit receipt showing the funds deposited into bank account or escrow

    Credit Items

    • Landlord’s name, address, and phone number (for verification of rental)
    • Explanations for any of the following items that may appear on your credit report:
      • Late payments
      • Credit inquiries in the last 90 days
      • Charge-offs
      • Collections
      • Judgments
      • Liens
    • Copy of bankruptcy papers if you have filed bankruptcy within the last seven years

    Other

    • Copy of purchase agreement (if you have already made an offer)
    • To document receipt of child support (if you desire to show it as income)
      • Copy of Divorce Settlement (to show the amount)
      • Copies of twelve months canceled checks to document actual receipt of fund

    FHA Loans

    • Copy of Social Security Card (or other documentation of social security number)
    • Copy of Driver’s license

    VA Loans

    • Copy of DD214

    Refinances

    • Copy of Note on existing loan
    • Copy of HUD1 Settlement Statement on existing loan
    • Name, address, phone number, loan number of existing loan/lender
  • Is Buying a Home Still a Smart Plan

    With the burst of the housing bubble, credit crisis, and millions of foreclosures across the country, you may wonder if buying a home is such a good idea after all. However, it’s important to consider all of the facts. The important message to take away from these events is not that buying a home is a bad idea, but that you must be smart about buying your home.

    The housing market, like every type of market, unavoidably has its ups and downs. That doesn’t mean buying a home is a bad investment. As a long-term investment, homeownership is still one of the best investments for individual households. Historically, real estate has consistently increased in value, despite shorter periods of depreciation due to local markets and/or national economic conditions. The data shows that homes generally appreciate about 5% per year.

    Savings & Investment

    Five percent may not seem like a great return on investment, but you have to think about it in the context of the situation. For example, let’s say you put 10% down on a $200,000 house. That’s a $20,000 down payment, or initial investment. At a 5% annual appreciation rate, your $200,000 home would gain $10,000 in value during the first year. Earning $10,000 on an investment of $20,000 is a whopping 50% return.

    For further perspective, let’s say instead of spending that $20,000 on a down payment, you invested it in the stock market. With a 5% return, you would gain only $1,000 in profit.

    Tax Benefits

    So now you’re saying that a home may have a higher return, but that’s before you consider all of the costs of home ownership, such as taxes, etc. Well, think of it this way: your property taxes as well as the interest on your mortgage are both tax deductible. You can deduct those costs from your income, thus reducing your overall taxable income. In other words, the government is subsidizing your home.

    Other Benefits

    It’s easy to get carried away with all of the economic reasons for home ownership, but it’s important to remember that not every reason is financial. Have you ever wanted to paint the walls of your apartment? Well when you’re renting, you can’t. Has anything in your apartment ever needed updating, but the landlord refused to do it? When you own a home, you can make the space yours in almost any way you want. And you benefit when you do home improvements, both financially and psychologically. Homes generally have more space, for storage, living, etc. than other living arrangements. Not to mention that you have space outdoors for barbecuing, pets, and kids. Owning your home carries with it a sense of pride, accomplishment, and even an elevated social status.

    So when you’re considering buying a home, consider the broad range of benefits that owning a home can have. And always make sure you have an experienced real estate agent and loan officer to help make sure you’re getting a home that is right for you, both financially and psychologically.

  • Insist on a Home Inspection

    A professional home inspection protects both you and the buyer. It allows both you and the buyer the opportunity to learn about the property’s defects.

    A home inspection usually covers the following:

    • Plumbing conditions – if there is leakage or clogging
    • Roofing conditions – the extent of deterioration, if there is leakage
    • Electrical conditions – if there are inadequate circuits or potential fire hazards
    • Structural problems – if there are problems with the underlying foundation of your home

    As a seller, the home inspection reports protect you because it establishes the actual condition of the property at the time of sale.