Author: admin

  • Living Trusts

    living trust

    Estate planners often recommend Living Trusts as a viable option when contemplating the manner in which to hold title to real property. When a property is held in a Living Trust, title companies have particular requirements to facilitate the transaction. While not comprehensive, answers to many commonly asked questions are below. If you have questions that are not answered below, your title company representative may be able to assist you, however, one may wish to seek legal counsel.

    Who are the parties to a Trust?

    A Family Trust is a typical trust in which the Husband and Wife are the Trustees and their children are the Beneficiaries. Those who establish the trust and transfer their property into it are known as Trustors or Settlors. The settlors usually appoint themselves as Trustees and they are the primary beneficiaries during their lifetime. After their passing, their children and grandchildren usually become the primary beneficiaries if the trust is to survive, or the beneficiaries receive distributions directly from the trust if it is to close out.

    What is a Living Trust?

    Sometimes called an Inter-vivos Trust, the Living Trust is created during the lifetime of the Settlors (as opposed to being created by their Wills after death) and usually terminates after they die and the body of the Trust is distributed to their beneficiaries.

    Can a Trust hold title to Real Property?

    No, the Trustee holds the property on behalf of the Trust.

    Is a Trust the best way to hold my property?

    Only your attorney or accountant can answer that question. Some common reasons for holding property in a Trust are to minimize or postpone death taxes, to avoid a time consuming probate, and/or to shield property from attack by certain unsecured creditors.

    What taxes can I avoid by putting my property in trust?

    Married persons can usually exempt a significant part of their assets from taxation and may postpone taxes after the first of them to die passes. You should check with your attorney or accountant before taking any action.

    Can I homestead property that is held in a Trust?

    Yes, if the property otherwise qualifies.

    Can a Trustee borrow money against the property?

    A Trustee can take any action permitted by the terms of the Trust, and the typical Trust Agreement does give the Trustee the authority to borrow and encumber real property. However, not all lenders will lend on a property held in trust, so check with your lender first.

    Can someone else hold title for me “in trust?”

    Some people who do not wish their names to show as titleholders make private arrangements with a third party Trustee; however, such an arrangement may be illegal, and is always inadvisable because the Trustee of record is the only one who is empowered to convey, or borrow against, the property, and a Title Insurer cannot protect you from a Trustee who is not acting in accordance with your wishes despite the existence of a private agreement you have with the Trustee.
  • Lead Poisoning

    lead paint

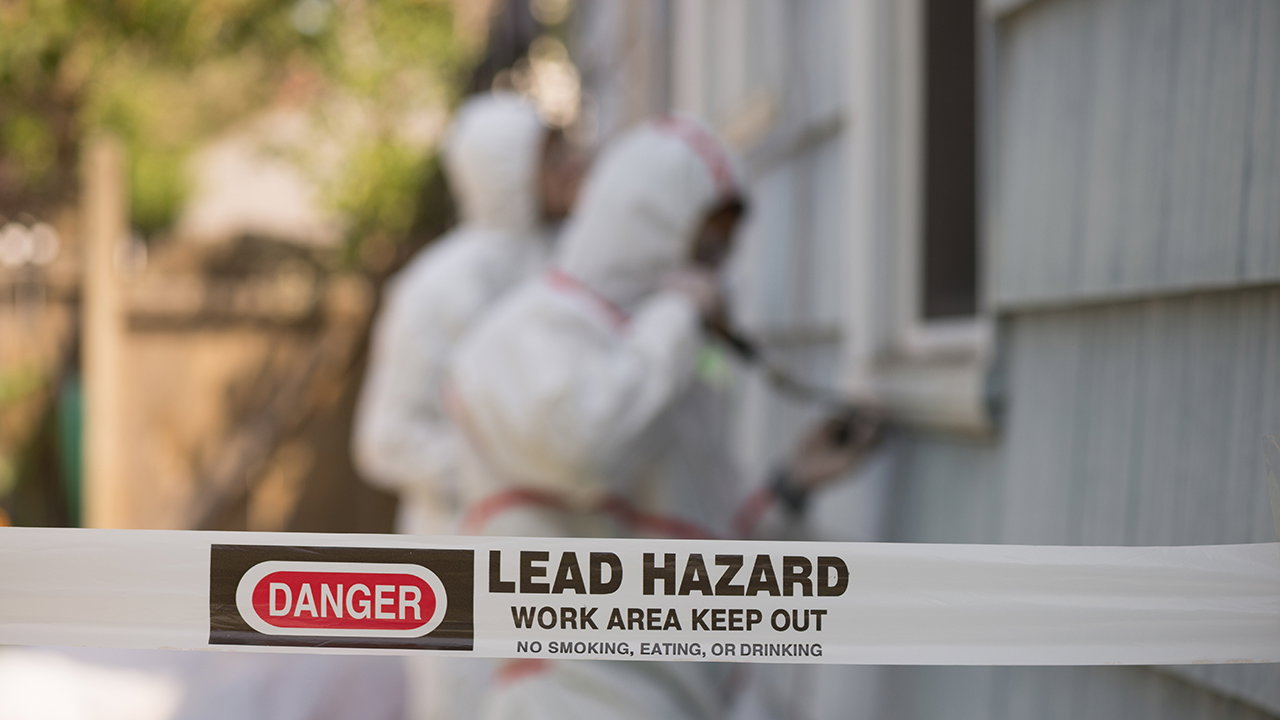
    Lead poisoning is a serious problem that can lead to adverse health problems. In children, high levels of lead can cause damage to the brain and nervous system, behavioral and learning problems, slow growth, and hearing problems. In adults, lead poisoning can cause reproductive problems, high blood pressure, digestive problems, nerve disorder, memory and concentration problems, and muscle and joint pain.

    Lead poisoning is especially a problem in cities with older buildings. Typically, lead is present in the paint from older buildings, in the water supply, and in the environment from cars and buses. Preventing lead poisoning in large cities, where there is such widespread possibility for exposure is both difficult and expensive. Federal programs have attempted to address this problem.

    Lead poisoning is also an issue that buyers and sellers need to consider. Houses that were built before 1978 probably have paint that contains lead. Federal law requires that sellers disclose known information on lead-based paint hazards before selling a house. Sales contracts must include a federal form about lead-based paint in the building. Buyers will have up to 10 days to check for lead hazards and are likely to stipulate corrections.

  • Land Contract

    An alternative to a non-conforming loan is the use of a land contract, which is allowed in some states. A land contract is an agreement between a buyer and a seller, where the buyer agrees to make periodic payments to the seller. The title to the property only transfers to the land contract buyer on fulfillment of the land contract obligations.

    A land contract can be helpful for those who need time to establish or improve their credit rating. There are only small closing costs, and payment can help establish a good mortgage payment record. This can help establish an overall good credit rating, and it is possible for the buyer to later refinance the land contract with a conforming loan.

    On the other hand, there are risks associated with land contracts. Land contract purchases are not necessarily recorded in the public record, and there are no guarantees that the seller will be able to transfer a clear title to the buyer upon fulfillment of the land contract. There also is no lender assuring that the purchase price for the property is justified, and no inspection of the property’s condition.

    Another alternative to a non-conforming loan is assuming the seller’s mortgage. By assuming a mortgage, if the mortgage is assumable, it is possible to save on closing costs, and may allow you to obtain a favorable interest rate.

  • Know Why You are Selling

    If you know exactly why you are selling then it is easier for you to follow the right plan of action for getting what you want.

    If you are a seller who needs to close a sale as quickly as possible, then you should know that getting the highest price possible is not one of your priorities. It does not mean that you won’t or cannot get the highest price, but it means that the price is not the deciding factor. A buyer who can give you a quick closing time will appeal much more to you than a buyer who can offer you more money but the negotiation and closing time drag on.

    It’s always good to know how low you will go in terms of selling price. This will help to eliminate some of the offers that you find simply offensive or ridiculous. Even though you should consider all offers seriously and take into consideration the terms of each offer, sometimes, if you know the bottom line and are strict about it, you can save yourself time.

    Once you know what your limits and reasons are, discuss them with your agent so that they can help you set your goals realistically. If you decide to list your home on your own, make sure you do research on the current market, and you get the proper advice you need in terms of legal issues, etc. The key is to be realistic and to know what your goals are so they can be met.

  • Items You Need When Applying For a Loan

    Have These Items Ready When You Apply For a Loan

    It used to be that lenders mailed out verifications to employers, banks, mortgage companies, and so on, in order to verify the data supplied by borrowers. Nowadays, the interest is often in speed and getting answers quickly so alternate documentation has become more widely used. Alternate documentation means that underwriting answers can be obtained with information supplied directly from the borrower instead of waiting around for verifications to come back in the mail.

    The following is required for most standardized loans as part of alternate documentation processing. Items may differ according to whether your loan is a conforming (Fannie Mae or Freddie Mac), non-conforming (jumbo) loan, government loan, or a portfolio loan.

    Verifications are still mailed out, but usually as part of quality control procedures.

    These are the things you need to supply to your lender to get a quick approval using alternate documentation

    Income Items

    • W2 forms for the last two years
    • Pay stubs covering a 30 day period
    • Federal tax returns (1040s) for the last two years, if:
      • you are self-employed
      • earn more than 25% of your income from commissions or bonuses
      • own rental property
      • or are in a career where you are likely to take non-reimbursed business expenses
    • Year-to-Date Profit and Loss Statement (for self employed)
    • Corporate or partnership tax returns (if applicable)
    • Pension Award letter (for retired individuals)
    • Social Security Award letters (for those on Social Security)

    Asset Items

    • Bank statements for previous two months (sometimes three) on all accounts. All pages.
    • Statements for two months on all stocks, mutual funds, bonds, etc.
    • Copy of most recent 401K statement (or other retirement assets)
    • Explanations for any large deposits and source of those funds
    • Copy of HUD1 Settlement Statement on recent sales of homes
    • Copy of Estimated HUD1 Settlement Statement if a previous home is for sale, but not yet closed
    • Gift letter (if some of the funds come as a gift from a family member)
    • Gifts can also require:
      • Verification of donor’s ability to make the gift (bank statement)
      • Copy of the check used to make the gift
      • Copy of the deposit receipt showing the funds deposited into bank account or escrow

    Credit Items

    • Landlord’s name, address, and phone number (for verification of rental)
    • Explanations for any of the following items that may appear on your credit report:
      • Late payments
      • Credit inquiries in the last 90 days
      • Charge-offs
      • Collections
      • Judgments
      • Liens
    • Copy of bankruptcy papers if you have filed bankruptcy within the last seven years

    Other

    • Copy of purchase agreement (if you have already made an offer)
    • To document receipt of child support (if you desire to show it as income)
      • Copy of Divorce Settlement (to show the amount)
      • Copies of twelve months canceled checks to document actual receipt of fund

    FHA Loans

    • Copy of Social Security Card (or other documentation of social security number)
    • Copy of Driver’s license

    VA Loans

    • Copy of DD214

    Refinances

    • Copy of Note on existing loan
    • Copy of HUD1 Settlement Statement on existing loan
    • Name, address, phone number, loan number of existing loan/lender

  • Is Buying a Home Still a Smart Plan

    With the burst of the housing bubble, credit crisis, and millions of foreclosures across the country, you may wonder if buying a home is such a good idea after all. However, it’s important to consider all of the facts. The important message to take away from these events is not that buying a home is a bad idea, but that you must be smart about buying your home.

    The housing market, like every type of market, unavoidably has its ups and downs. That doesn’t mean buying a home is a bad investment. As a long-term investment, homeownership is still one of the best investments for individual households. Historically, real estate has consistently increased in value, despite shorter periods of depreciation due to local markets and/or national economic conditions. The data shows that homes generally appreciate about 5% per year.

    Savings & Investment

    Five percent may not seem like a great return on investment, but you have to think about it in the context of the situation. For example, let’s say you put 10% down on a $200,000 house. That’s a $20,000 down payment, or initial investment. At a 5% annual appreciation rate, your $200,000 home would gain $10,000 in value during the first year. Earning $10,000 on an investment of $20,000 is a whopping 50% return.

    For further perspective, let’s say instead of spending that $20,000 on a down payment, you invested it in the stock market. With a 5% return, you would gain only $1,000 in profit.

    Tax Benefits

    So now you’re saying that a home may have a higher return, but that’s before you consider all of the costs of home ownership, such as taxes, etc. Well, think of it this way: your property taxes as well as the interest on your mortgage are both tax deductible. You can deduct those costs from your income, thus reducing your overall taxable income. In other words, the government is subsidizing your home.

    Other Benefits

    It’s easy to get carried away with all of the economic reasons for home ownership, but it’s important to remember that not every reason is financial. Have you ever wanted to paint the walls of your apartment? Well when you’re renting, you can’t. Has anything in your apartment ever needed updating, but the landlord refused to do it? When you own a home, you can make the space yours in almost any way you want. And you benefit when you do home improvements, both financially and psychologically. Homes generally have more space, for storage, living, etc. than other living arrangements. Not to mention that you have space outdoors for barbecuing, pets, and kids. Owning your home carries with it a sense of pride, accomplishment, and even an elevated social status.

    So when you’re considering buying a home, consider the broad range of benefits that owning a home can have. And always make sure you have an experienced real estate agent and loan officer to help make sure you’re getting a home that is right for you, both financially and psychologically.

  • Insist on a Home Inspection

    A professional home inspection protects both you and the buyer. It allows both you and the buyer the opportunity to learn about the property’s defects.

    A home inspection usually covers the following:

    • Plumbing conditions – if there is leakage or clogging
    • Roofing conditions – the extent of deterioration, if there is leakage
    • Electrical conditions – if there are inadequate circuits or potential fire hazards
    • Structural problems – if there are problems with the underlying foundation of your home

    As a seller, the home inspection reports protect you because it establishes the actual condition of the property at the time of sale.

  • Importance of Inspection

    As a buyer, you are entitled to know exactly what you are getting. Don’t take anything for granted, not even what you see or what the seller or listing agent tell you. A professional home inspection is something you MUST do, whether you are buying an existing home or a new one. An inspection is an opportunity to have an expert look closely at the property you are considering purchasing and getting both an oral and written opinion as to its condition.

    Beforehand, make sure the report will be done by a professional organization, such as a local trade organization or a national trade organization such as ASHI (American Society of Home Inspection). Not only should you never skip an inspection, but also you should be present with the inspector during the inspection. This gives you a chance to ask questions about the property and get answers that are not biased. In addition, the oral comments are typically more revealing and detailed than what you will find on the written report. Once the inspection is complete, review the inspection report carefully.

    You have to demand an inspection when you present your offer. It must be written in as a contingency. If you do not approve the inspection report, then do not buy the home. Most real estate contracts automatically provide an inspection contingency.

  • Hot, Normal, and Cold Markets

    Hot Market

    This is an extremely competitive market and is advantageous to the seller. Sometimes, homes will sell as soon as they are listed or even before homes are listed. Typically, during a hot market, multiple offers will be made on each home and more often than not, homes will sell for more than the asking price. It is even more crucial to be prepared and to be ready as a buyer when the market is hot. It can be easy to get caught up in the bid for a home, but if you are prepared (pre-approved, solid in price range, realistic about your needs), it is easier to remain focused on your housing needs and price range.

    Normal Market

    In a normal market, there is a fairly large number of homes available and an average number of buyers. This market does not necessarily favor the buyer or the seller. A seller may not have as many offers on their home, but he or she may not be desperate to sell either. Again, it is the buyer’s responsibility to be prepared. During a normal market, the chances to negotiate are higher than in a hot market. As a buyer, you can expect to make offers at lower than the asking price and negotiate a price at least somewhat less than what the sellers are asking.

    Cold Market

    In a cold market, houses may be listed for more than a year and the prices of houses listed may drop considerably. This market is advantageous to the buyer. As a buyer, you have the time to make an offer that works to your best interest. It is not uncommon to low-ball and to find that sellers are accommodating to meet your needs. Keep in mind that even though this market is a great time for buyers, you do not want to lose your dream home by being unrealistic. Your goal is to get your dream home at the best possible price.

  • Getting the Highest Price in the Shortest Time

    In order to get the highest price in the shortest time, you need to know how to market your home. The better you market your home, the more offers you will get. And the more offers you get, the more choices you have to get the price and terms you want.

    The most important factor of marketing your home is pricing it right. Your price should be adjusted to reflect the market and your property’s worth. The key is to get as many people as possible checking out your fairly priced property. If your property is not priced fairly, there will be no buyers because your price is set too high.

    Another important factor is the condition of your home. Make sure that your home looks ready to be sold. Fix any defects (peeling or faded paint, cracks, stains, etc.) Condition alone can sometimes prompt fast buying decisions. Not only should you fix any defects, but consider upgrading your home by making major repairs and cosmetic improvements before selling. A nice looking home triggers the emotional response that can lead to a financial response.

    Learn how to negotiate the best terms for all parties involved. Terms are another factor that may be adjusted to attract buyers. If you insist on getting your asking price, think of what you can offer to the buyers. For example, improvements you’ve made or even offering seller financing at a lower than market interest rate on a portion of the sale price. Convince them why they should be paying the price you have set.

    Lastly, get the buzz out about your home. List your house with a hot agent that ensures your house is listed on the MLS and on the Internet. On your own, get the word out. It should always be visible to passersby that your house is for sale, whether it is through signs, local advertisements or you telling friends, family, and acquaintances.

Share with