Author: admin

  • WHAT’S A FICO®?

    What is a FICO® Score?

    FICO® stands for Fair Isaac & Company and is the name for the most well known credit scoring system, used by Experian. The credit bureau’s computer evaluates a complete credit profile and assigns a score, which is used to estimate credit worthiness. Each of the three bureaus (Experian, Trans Union, Equifax) employs its own scoring system, so a given person will usually have 3 separate scores. Someone with a higher score will be viewed as a better risk than someone with a lower score. Typically, scores will range from about 600 to 700 or above, although some cases will be outside this range.

    What Kind of Score Do I Need for a Home Loan?

    There are as many answers to this question as there are loan programs available. Most lenders will take the average of all 3 scores to evaluate an application. Niche loans, such as Easy Qualifier and low down payment loans will have higher FICO® requirements.

    How is My Score Determined?

    The FICO® model has 5 main elements:

    1. Past payment history (about 35% of score) The fewer the late payments the better. Recent late payments will have a much greater impact than a very old Bankruptcy with perfect credit since.
      Myth – paying off cards with recent late payments will fix things. Payoffs do not affect payment history.
    2. Credit use (about 30% of score) Low balances across several cards is better than the same balance concentrated on a few cards used closer to maximums. Too many cards can bring down the score, but closing accounts can often do more harm than good if the entire profile is not considered. BE CAREFUL WHEN CLOSING ACCOUNTS!
    3. Length of credit history (15% of score) The longer accounts have been open the better for the score. Opening new accounts and closing seasoned accounts can bring down a score a great deal.
    4. Types of credit used (10% of score) Finance company accounts score lower than bank or department store accounts.
    5. Inquiries (10% of score) Multiple inquiries can be a risk if several cards are applied for or other accounts are close to maxed out. Multiple mortgage or car inquiries within a 14 day period are counted as one inquiry.

    How Can I Raise My Score

    Your score can only be changed by the way that item is reported directly to the credit bureaus (Experian, TU, Equifax). Written confirmation from the creditor is required. It is best to make these corrections before you try to purchase a home, because you can never be sure the exact impact a change will have on your score.

    What Does This Mean to Me?

    You should have your credit reviewed BEFORE you look for a home, and work with a PROFESSIONAL loan officer to make sure your loan is based on the most accurate information.

  • Types of Mortgage Lenders

    Mortgage Bankers

    Mortgage Bankers are lenders that are large enough to originate loans and create pools of loans, which are then sold directly to Fannie Mae, Freddie Mac, Ginnie Mae, jumbo loan investors, and others. Any company that does this is considered to be a mortgage banker.

    Some companies don’t sell directly to those major investors, but sell their loans to the mortgage bankers. They often refer to themselves as mortgage bankers as well. Since they are actually engaging in the selling of loans, there is some justification for using this label. The point is that you cannot reliably determine the size or strength of a particular lender based on whether or not they identify themselves as a mortgage banker.

    Portfolio Lenders

    An institution that lends their own money and originates loans for itself is called a portfolio lender. This is because they are lending for their own portfolio of loans and not worried about being able to immediately sell them on the secondary market. Because of this, they don’t have to obey Fannie/Freddie guidelines and can create their own rules for determining credit worthiness. Usually these institutions are larger banks and savings & loans.

    Quite often only a portion of their loan programs are a portfolio product. If they are offering fixed rate loans or government loans, they are certainly engaging in mortgage banking as well as portfolio lending.

    Once a borrower has made the payments on a portfolio loan for over a year without any late payments, the loan is considered seasoned. Once a loan has a track history of timely payments it becomes marketable, even if it does not meet Freddie/Fannie guidelines.

    Selling these seasoned loans frees up more money for the portfolio lender to make additional loans. If they are sold, they are packaged into pools and sold on the secondary market. You will probably not even realize your loan is sold because, quite likely, you will still make your loan payments to the same lender, which has now become your servicer.

    Direct Lenders

    Lenders are considered to be direct lenders if they fund their own loans. A direct lender can range anywhere from the biggest lender to a very tiny one. Banks and savings & loans obviously have deposits with which they can fund loans, but they usually use warehouse lines of credit for drawing the money to fund the loans. Smaller institutions also have warehouse lines of credit from which they draw money to fund loans.

    Direct lenders usually fit into the category of mortgage bankers or portfolio lenders, but not always.

    Correspondents

    Correspondent is usually a term that refers to a company that originates and closes home loans in their own name, then sells them individually to a larger lender, called a sponsor. The sponsor acts as the mortgage banker, re-selling the loan to Ginnie Mae, Fannie Mae, or Freddie Mac as part of a pool. The correspondent may fund the loans themselves or funding may take place from the larger company. Either way, the sponsor usually underwrites the loan.

    It is almost like being a mortgage broker, except that there is usually a very strong relationship between the correspondent and their sponsor.

    Mortgage Brokers

    Mortgage Brokers are companies that originate loans with the intention of brokering them to lending institutions. A broker has established relationships with these companies. Underwriting and funding takes place at the larger institutions. Many mortgage brokers are also correspondents.

    Mortgage brokers deal with lending institutions that have a wholesale loan department.

    Wholesale Lenders

    Most mortgage bankers and portfolio lenders also act as wholesale lenders, catering to mortgage brokers for loan origination. Some wholesale lenders do not even have their own retail branches, relying solely on mortgage brokers for their loans. These wholesale divisions offer loans to mortgage brokers at a lower cost than their retail branches offer them to the general public. The mortgage broker then adds on his fee. The result for the borrower is that the loan costs about the same as if he obtained a loan directly from a retail branch of the wholesale lender.

    Banks and savings & loans usually operate as portfolio lenders, mortgage bankers, or some combination of both.

    Credit Unions usually seem to operate as correspondents, although a large one could act as a portfolio lender or a mortgage banker.

  • The Biweekly Mortgage – Who Needs It?

    Have you received an advertisement offering to save you thousands of dollars on your thirty-year mortgage and cut years off your payments? With email spam becoming more pervasive as everyone tries to get rich quick on the Internet, these ads are popping up with troublesome regularity.

    The ads promote a Biweekly Mortgage and for the most part, do not come from a mortgage lender. Exclamation points punctuate practically every claim:

    • No closing costs!
    • No refinancing!
    • No points!
    • No credit check!
    • No appraisal!
    • Save thousands!
    • Cut years off your mortgage!

    To achieve these wonderful savings all you have to do is allow half of your mortgage payment to be deducted from your checking account every two weeks. It’s easy. Of course, there is a small set-up fee and usually a transaction fee with every automatic deduction.

    Essentially, the ads are truthful in almost every respect.

    They just want to charge you money for something you can do on your own for free.

    The Basics:

    Normally, you make twelve mortgage payments a year. Since there are fifty-two weeks in a year, a biweekly mortgage equals 26 half-payments a year. The equivalent would be making thirteen mortgage payments a year instead of twelve. By applying that extra payment directly to the loan balance as a principal reduction, your loan amortizes more quickly, requiring fewer payments.

    You save money. The ads are true.

    How it Actually Works:

    You cannot simply mail in half a payment every two weeks to your mortgage lender. Since they do not accept partial payments for legal and accounting reasons, the mortgage company would just mail your half-payment back to you.

    Instead, the biweekly mortgage company is an intermediary between you and your mortgage lender. They automatically debit your checking account every two weeks for half of your mortgage payment then place your funds into a trust account. Basically, this is just a holding account for your money. In another two weeks, there is another automatic deduction from your checking account, and so on. When your mortgage payment is due, your funds are withdrawn from the trust account and forwarded to your mortgage lender.

    Since you are placing funds into the trust account faster than your mortgage payments are due, you eventually accumulate enough money to make an extra payment. The way the cycle works, this occurs once a year. he extra payment is applied directly to your principal balance, which causes your loan to amortize faster, pay off more quickly and save you thousands of dollars.

    Potential Problems with the Trust Account

    Because your funds are held in the trust account until your mortgage payment is due, there are potential dangers. Not only are your funds held in this account, but so are the funds of everyone else enrolled in the biweekly program. That is a lot of money.

    Most likely, there will be no problems.

    However, if there are accounting errors, mismanagement, or even fraud, your mortgage payment might not get made. The first hint of a problem will probably be a phone call or letter from your mortgage lender, but not until after your payment is already late. Since responsibility for making the payment rests with you and not the biweekly payment company, you may find yourself digging into your personal savings to make the payment directly — even though the biweekly payment company has already collected your funds.

    Later you can work out the trust account problem with your biweekly payment company.

    The Cost of the Biweekly Mortgage

    There is usually a set-up fee that runs between $195 and $350, depending on how much sales commission is paid to the individual or company setting up the account for you. You also pay a transaction fee each time there is an automatic deduction from your checking account and sometimes also when the payment is made to your mortgage lender. There may also be a periodic maintenance fee.

    Meanwhile, whoever controls the trust account is earning interest on your money.

    Savings of the Biweekly Mortgage

    By making principal reductions using the biweekly mortgage program, your mortgage will amortize more quickly, saving you money. How quickly your loan pays off depends on your interest rate and when you begin making the biweekly payments.

    On a $100,000 loan at an interest rate of eight percent, your first principal reduction would probably be a year from now. Assuming the principal reduction is equal to one monthly payment ($733.76), you would save $43,852 over the life of the loan and pay it off almost seven years early.

    However, you have to deduct from those savings any amounts you paid in set-up, transaction, and maintenance fees.

    No-Cost Alternatives to the Biweekly Mortgage

    Instead of hiring a company to manage your biweekly payment, you could accomplish essentially the same thing on your own for free. Just take your monthly payment, divide it by twelve, and add that amount to your monthly mortgage payment. Be sure to earmark it as a principal reduction.

    The first way you save is that you do not have to pay any fees to anyone. It’s free.

    In addition to not paying fees — using the same example as above — your total savings on the mortgage would be $45,904. Plus the loan would be paid off three months quicker than with the biweekly mortgage. The reason you save more is because you are making a principal reduction each month, instead of waiting for funds to accumulate so that you can make one principal reduction a year.

    Self-Discipline?

    The biweekly mortgage companies claim that homeowners are not disciplined enough to follow through with principal reduction plans on their own. They suggest the reason for setting up the biweekly mortgage enforces discipline upon you, and by doing so, they save you money.

    However, in this technologically advanced age, banking online and automatic deductions are readily available. You can set up your own automatic deductions including the additional principal reduction and have it go directly to your mortgage lender. Since the deduction occurs automatically, just like with the biweekly mortgages, self-discipline is not a problem. Once again, you don’t have to pay anyone to do it for you and you save even more money.

    Conclusion

    The biweekly mortgage plans do not really do anything except move your money around and charge you for it. Plus, even though the danger is negligible, you must trust someone else to hold your money for you. If you can do the very same thing for free, plus save yourself even more money by doing it on your own, why pay someone else?

    The biweekly mortgage plan – who needs it?

    If your goal is principal reduction and saving money, then it is a good plan. If you do it on your own instead of paying someone else to do it for you, then it is a great plan.
  • 3 bedroom 2 bath Home Sandpoint Home Located Base of Schweitzer Mountain

    3 bedroom 2 bath Home Sandpoint Home Located Base of Schweitzer Mountain

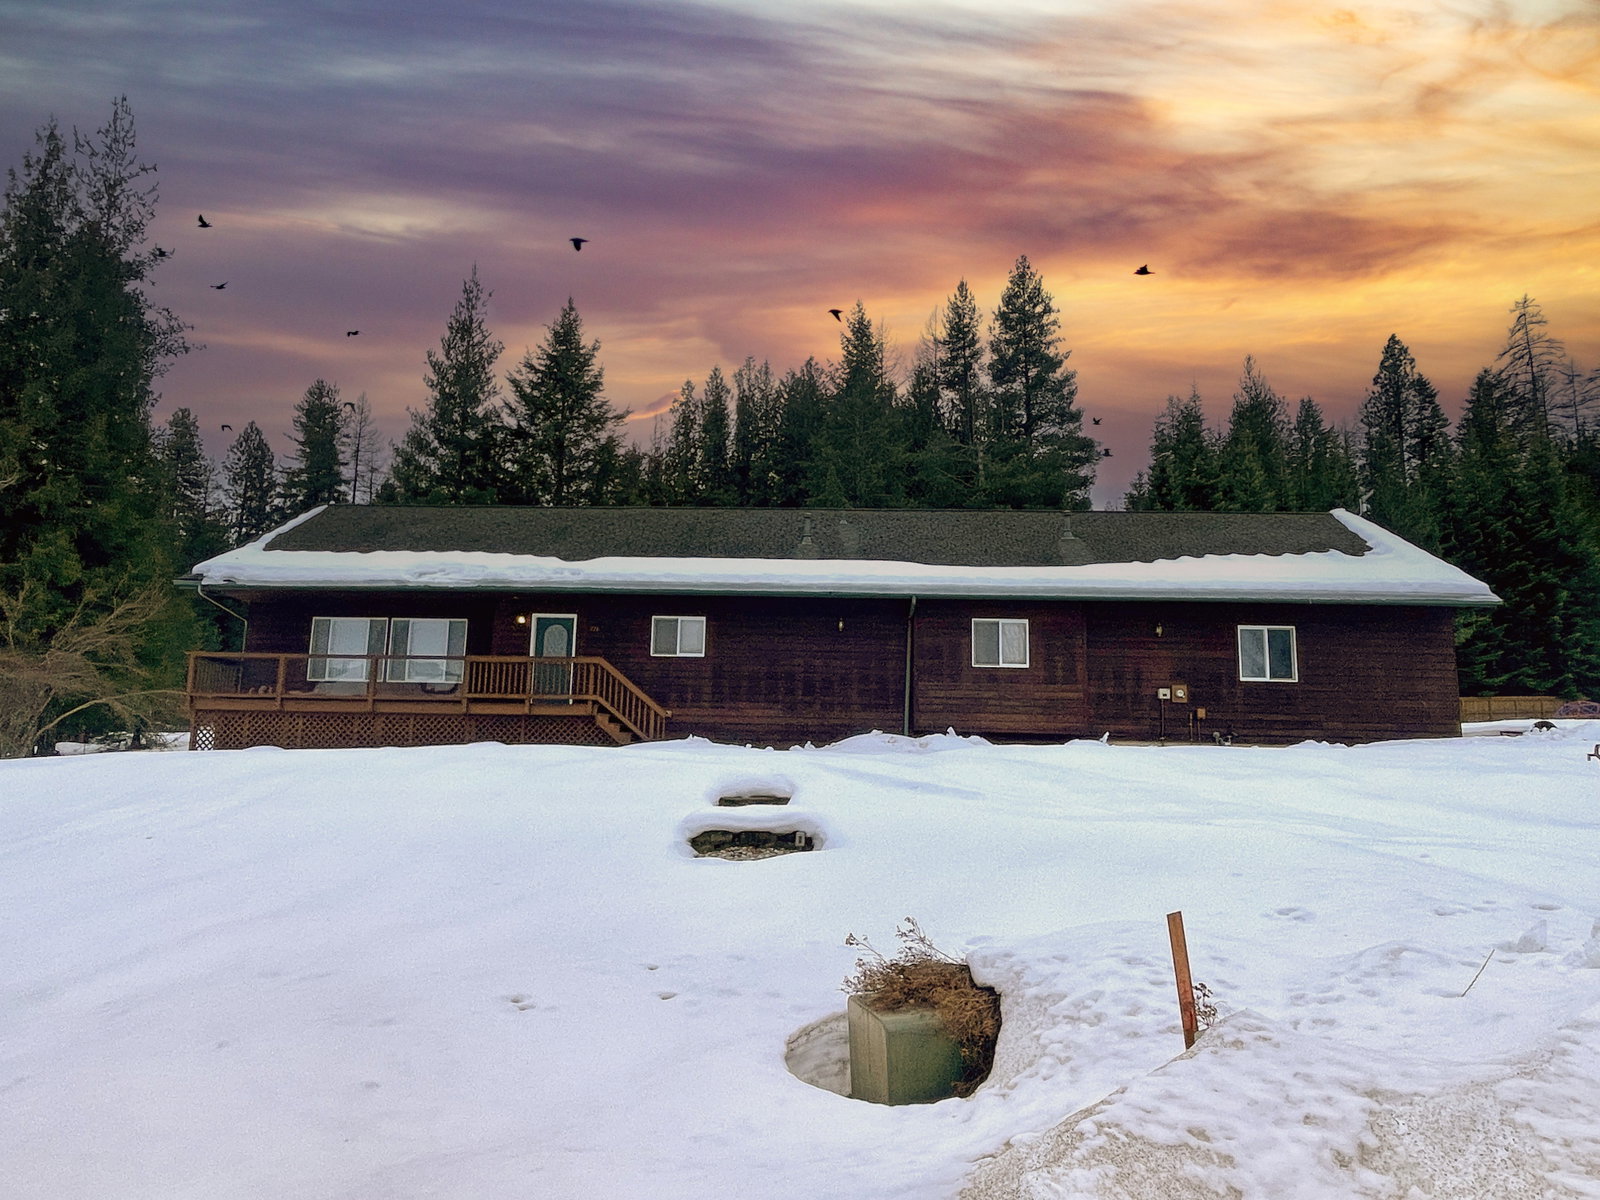
    Sandpoint Realty recent listing (courtesy Rain Silverhawk) is an excellent example of location-location-location. 

    Sandpoint Realty Sweetgrass Sandpoint Idaho Listing

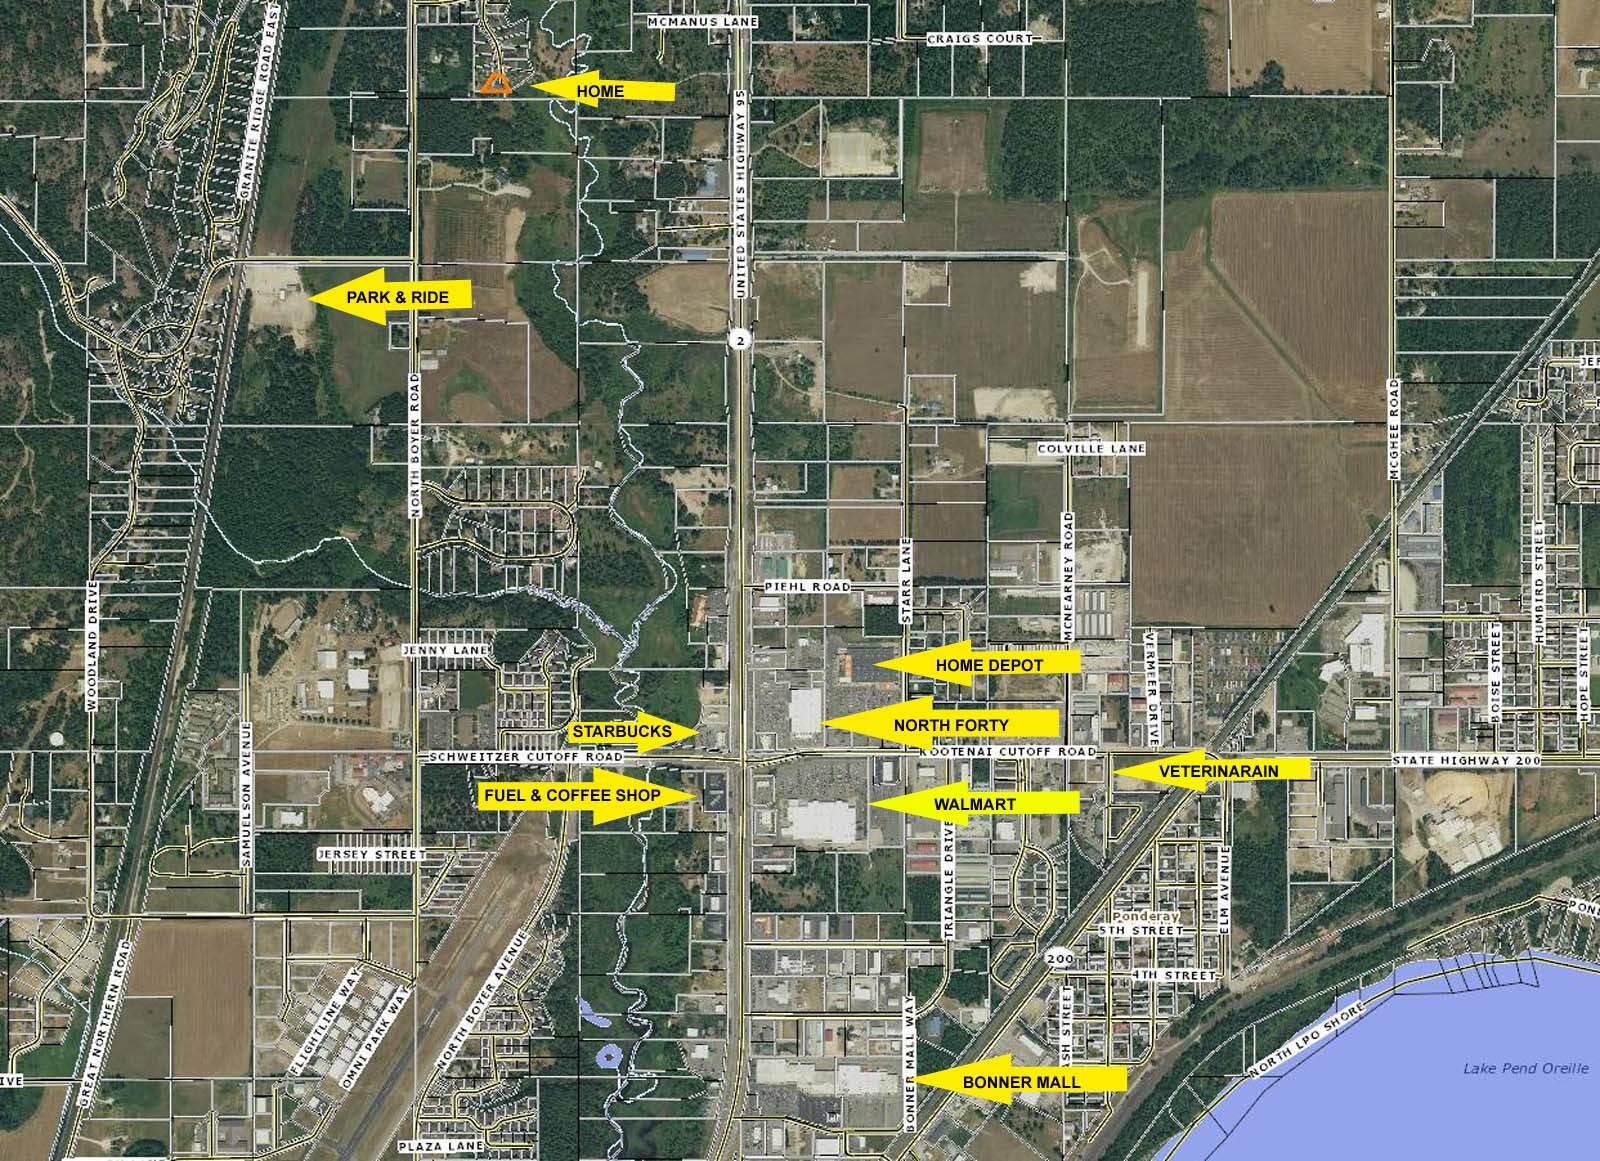
    Just at the upper portion of the aerial you can see the home at the outskirts of Sandpoint Idaho & Ponderay Idaho city limits.  Marked are some nearby well known locations.  Also within the same radius, and not marked, are several restaurants, hotels, medical, grocery, Post Office, multi screen theater, and of course a fast food haven along Hwy 95.  

    Also of note should be that Schweitzer Ski Resort Village is but 9 miles from their base Park & Ride, if one chooses to drive rather than take the shuttle.  Access to Highway 95 (highway 2 leg to Bonners Ferry) and Highway 200 (to Clark Fork and Hope Idaho) very simple and accessible.

    As seen in the short YouTube video above the home alone, on this very sought after and secluded street, is reason enough to set up a time to view, if not at least ask for additional information.  Add the benefits of these city comforts, shown on the aerial, all being less than 2 miles away, and this a must see home in Sandpoint Idaho.

    Selkirk MLS Listing 20230154    $599,000

    ‘Experience the Difference’ in working with a full time Professional Sandpoint Realty REALTOR®.  Your wants and needs will always be my priorities.  

    Mark Don McInnes

    Broker – REALTOR®

    208 255-6227

    SandpointNorthIdaho.com – North Idaho Home & Land Searches

    Sandpoint Realty LLC

    1205 Highway 2

    Sandpoint, Idaho 83864

  • Bonners Ferry Idaho Home for Sale – 4 bedroom 2 bath

    Lovely nostalgic in town Bonners Ferry Home for sale with end of road privacy.  This charming 4 bedroom, plus 5th non conforming, and 2 baths home has 1,822 sq. ft.,  and sits at end of the road on a double lot totaling .35 acres.  Close to all Bonners Ferry amenities, this is a home very much worth looking at.
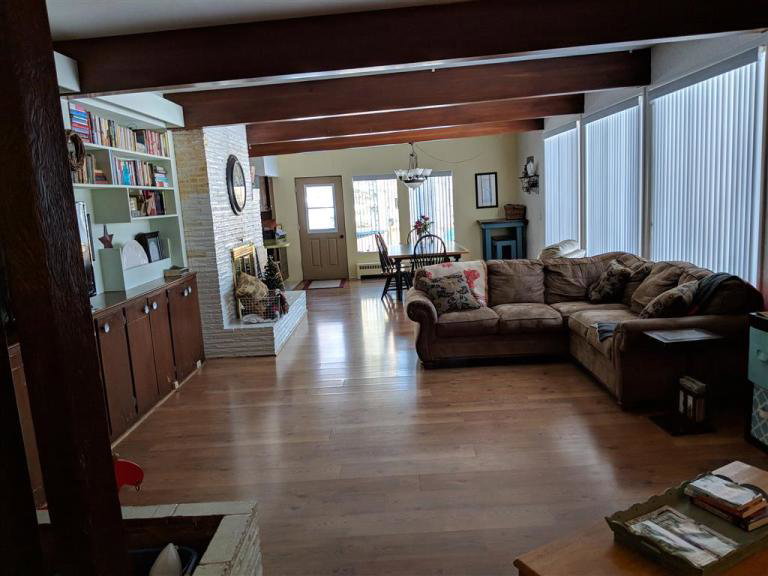
    Main floor living with kitchen opening to large dining and living room area.  Over sized windows bring the warmth of the day in with natural sunlight.  Master bedroom and 2 additional bedrooms on the main floor as well.  Step from the covered main entrance, off the 2 car carport, into hall way leading either to the kitchen or living room  Kitchen offers plenty of cupboard space and views to the large yard and tree house, along with filtered views to downtown Bonners Ferry.

    Large 4th bedroom is on lower level along with a small shop / craft room plus a pantry – storage room.  Master bath has been redone with stand alone bath tub.  Very cute bathroom.  The attic offers the hideaway bonus room, with the possible 5th non conforming bedroom.
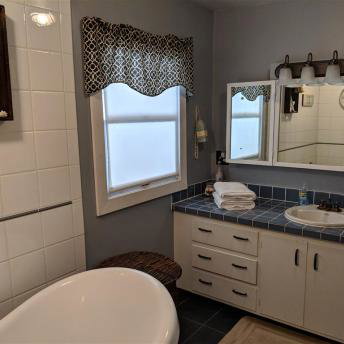
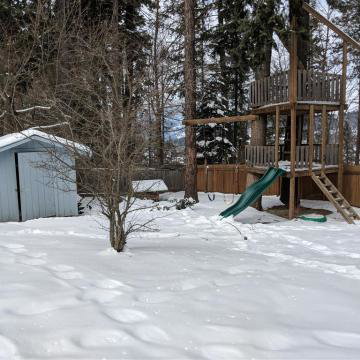
    The double lot allows for plenty of fenced outside room with a cool tree house.  There is a covered patio and open deck.

    This home includes an in ground pool although there is no value given with winter still upon us  and can not be sure of pump house condition.

    Experience the difference ‘Living In North Idaho’ will make.  Contact me as your local North Idaho Real Estate resource.

    6537 Jefferson – Bonners Ferry – Idaho 83805
  • Sagle Idaho Pilots Getaway for Sale

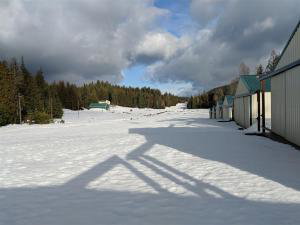
    Spring is starting to show itself early in North Idaho.  Snow is disappearing from the valley floors and grass revealing itself.  With the warmer temperatures interest is increasing in this Sagle Idaho Pilots Getaway.  Interestingly there are two available and with different needs met at Timber Basin Airpark in Sagle Idaho.


    Sagle Idaho Pilots Getaway

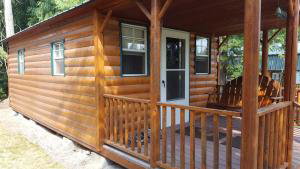
    Want to fly into and Sagle Idaho Pilots Getawayland with your 5 star hotel room with hangar right there?  This warm cozy cabin offers just that.  Cabin has 336 Square Feet with covered porch looking across the runway to your personal hangar.  Murphy bed, full bath, and kitchenette make this the perfect base for all your North Idaho Outdoor Adventures.
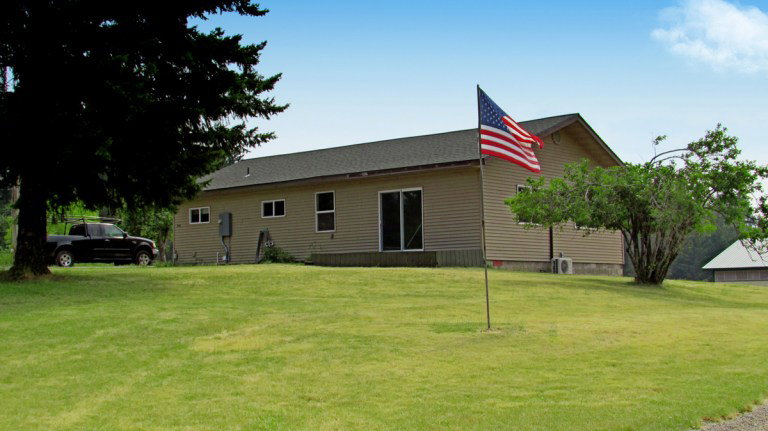
     

    Selkirk MLS 20173031

    Sagle Idaho Pilots Getaway

    Frame home is the original home to the Timber Basin Airpark.  Completely remodeled in 2017 with new electric, plumbing, paint, carpet, linoleum.  Surprising large square footage at 1,372.  Large open living room, dining room and kitchen with bathrooms attached to each bedroom.  Maintain this house as your summer getaway, or with addition of cadet heaters, or something similar, turn the home into year round living.

    A hangar is approved to be built across the runway from the home.  42 X 50 maximum footprint allows for plenty of inside room.

    Selkirk MLS 20172777 $189,000.00

    Included with either listing is 1/14 share to Timber Basin Airpark.  2,300 foot runway and plans for pilot lounge.  Airpark owns approximately 80 acres which each membership of Timber Basin Airpark has shared ownership.  Pilots license, whether active or not, is required to purchase at Timber Basin Airpark.

    Take a look at either one of these fantastic opportunities now.  Be ready for the spring and summer months rather than waiting.  Beautiful Lake Pend Oreille Bottle Bay and Garfield Bay only minutes away.  Downtown Sandpoint Idaho just across the Longbridge.

  • Sandpoint City Homes for Sale February 2018 – ‘83864’

    Sandpoint City sits within the zip code of 83864.  A very large area, with so much diversification it is very difficult to give any one single report that is accurate to all that is available in the 83864 area code.  Currently there are 32 Sandpoint City Homes for Sale.  Basic criteria for search results below.
    Criteria, for Selkirk Multiple Listing Search, MLS, is basic.  $750,000 maximum list price.  1 bedroom 1 bath minimum.  Searched as ‘in Sandpoint City’.  Single Family, Condos, Townhouses all included.  The search results do not include ‘For Sale by Owner’ or Coeur D’ Alene MLS results.  The results do show the trend though, that will be consistent without those results added in.

    Sandpoint City Homes for Sale

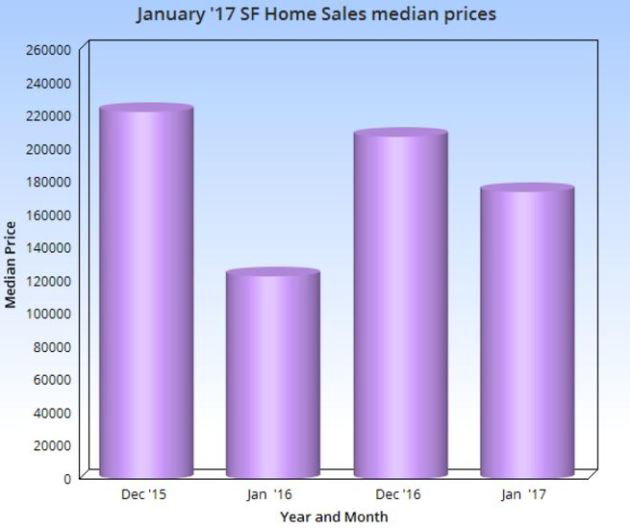
    January 2016 showed 4 homes sold.  Median Price of $153,000.  120 days on market.  January 2017 showed 2 homes sold with a Median Price of $174,500 and 66 days on Market.  An impressive 14Sandpoint City Homes for Sale% increase in ‘Sold’ price for the one year.
    1st quarter 2016 has 20 homes being sold with a median sold price of $209,000.  And 125 days on market.  1st quarter 2017 shows 18 homes sold with modest increase for median sold price of $218,000.  98 days on market.

    January 2018 has me shaking my head.  I went back twice to double check the results, along with active presently available.  8 homes sold.  Double that of 2016 and 4 times as many 2017.  Median sold price of $230,000 with days on market at 122.  An impressive 24% increase in median sold price.  With the 8 homes sold this January, Sandpoint City is easily on track to surpass sales for 1st quarter of both 2016 and 2017.

    Current inventory of 32 with January Sold’s at 8, along with the 122 days on market shows a 4 month inventory.  What is phenomenal is the median listing price at the current time.  $314,450.00.  While not the sold price, it is 44% above the median sold price of 2017’s $218,000.00.  Incredible.

    I do not for see Sandpoint City Home Sales slowing.  I question whether they can sustain, or realize, the jump in market price that is showing between current listing price and even sold’s of just one month ago.  While great for sellers it is putting a strain on buyers and the market in general.

  • Keller Williams Realty #1 – 2017

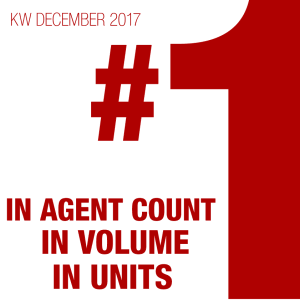
    Keller Williams Coeur D’ Alene – Sandpoint announced a special meeting recently.  Upon arriving, to the Coeur D’ Alene training room, champagne was being served.  It is official.  Keller Williams Realty #1 in 2017.  All 3 categories.  Agent Count.  Volume.  Units Sold.

    Keller Williams Realty #1

    Keller William’s recent Vision Breakfast, in Coeur D’ Alene was full of excitement for good reason.  New operating principles Dennis and Pam Ranch revealed plans for a new Keller Williams Coeur D’ Alene office building to be completed by March 2019.

    The Coeur D’ Alene – Sandpoint office has moved to the #2 spot in North Idaho market.  This, while being impressive is but a stepping stone to future goals.  #1 in view and sought after with commitment and passion.

    Keller Williams Realty #1

    Coming next week is the Keller Williams Family Reunion 2018.  Being held in Anaheim California, agents from across the country will be there to be educated, given future plans for Keller Williams Realty, and network with one another.

    Keller Williams Realty #1 does not happen by accident.  It is planned with appropriate actions taken to accomplish.  I am grateful to be associated with Keller Williams Realty.  For not only the opportunities made possible, but the education provided, along with a culture that promotes family, personal growth and business to walk hand in hand.

  • North Idaho Winter Snow

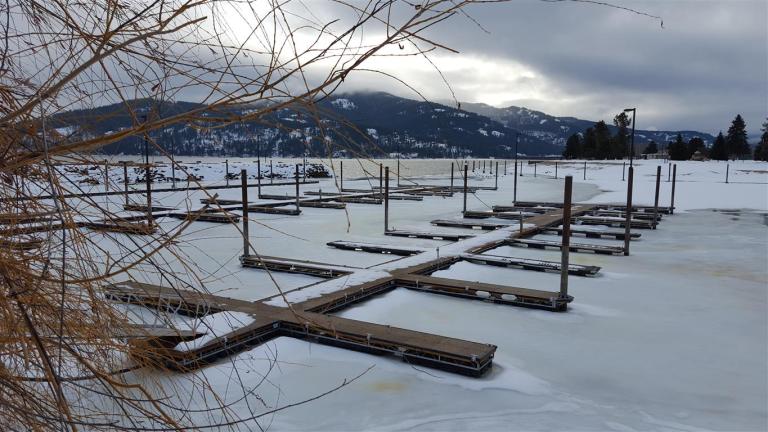
    Warmer temperatures have helped clearing of snow from valley floors but only minimally.  And the beautiful scenes are not to be spoiled by only a few days of marginally warmer weather.  The reality to North Idaho winter storms as in any snow state, is that there are two sides to the coin, scales always kept even, or what ever phrase you care to use.  North Idaho Winter Snow brings forth unique serene beauty everywhere, and it also adds work and obstacles for all.

    The above picture showing the harsh cold and at the same time beauty found early morning at Windbag Marina in Sandpoint Idaho.  Docks filled with sailboats, during the summer and fall months, are surrounded by ice and snow as well as deserted. Wind swept Lake Pend Oreille sits empty.  Turning the opposite direction will show Schweitzer Ski Resort to be hidden by low dark ominous clouds.

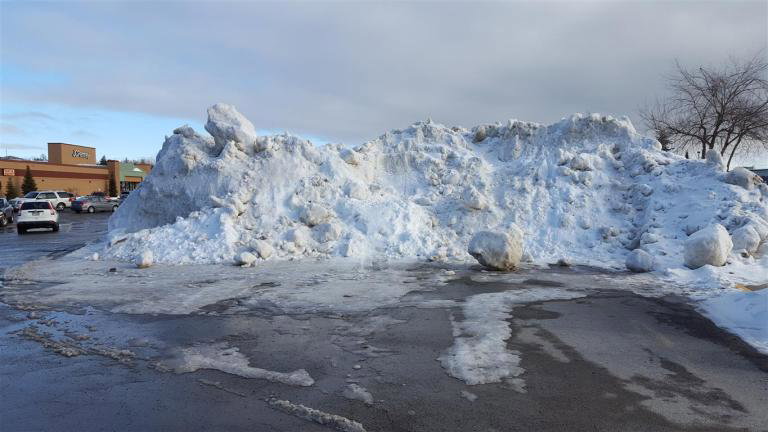
    In contrast to this beauty North Idaho Winter Snow brings obstacles for all. Difficult driving conditions, additional work, freezing pipes, snow removal of all kinds, roofs for business, or personal being extremely important.  The 2nd picture is at Bonners Mall in Ponderay.  Snow removal for parking being plowed and piled as far out of the way as possible, and yet still obstructing drive ways and parking.

    Yet to a person I am guessing we all agree the beauty far outweighs the inconveniences of the latter.

  • Sagle Idaho 3 bedroom Home For Sale – $79,000.00

    While it is argued there are no longer good values to be found in North Idaho housing, this Sagle Idaho 3 bedroom Home For Sale gives proof to just the opposite.  At $82,000 (Improved price as of January 22, 2018 – $79,000) it would be difficult to find rent less expensive,at this time, than the mortgage payment of this home.

    Sagle Idaho 3 bedroom home for sale

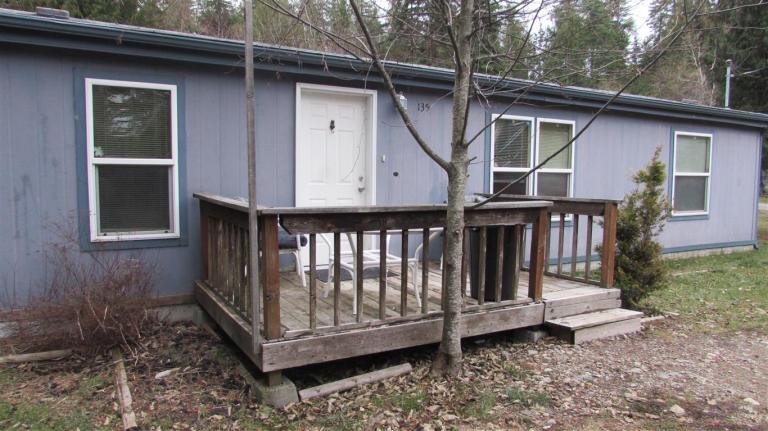
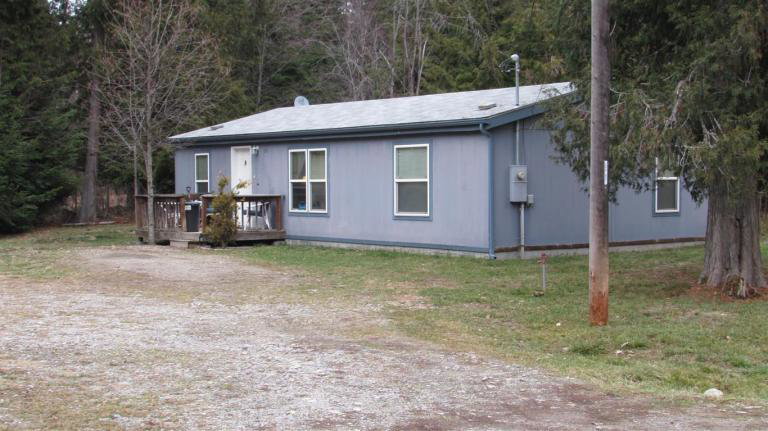
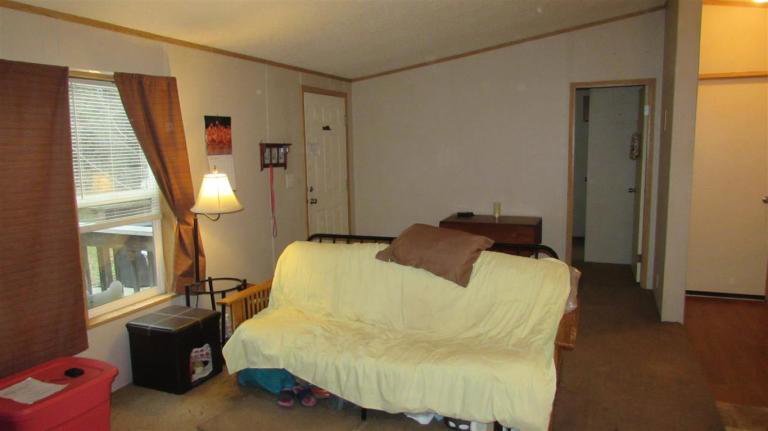
    Three bedrooms, 2 baths, and 1,096 sq. ft.  with community water and private septic.  Real property manufactured home located on .34 acres and less than 9 miles to Highway 95 with either Dufort or Sagle Roads.  Minutes to beautiful Garfield Bay boat launch, marina, camp ground and park.

    Located at 135 Cedar Hill in Sagle Idaho this home and 10X16 storage shed, situated on .34 acres, allows room for garage / shop and or garden area.  2 of the 3 bedrooms separated from the master bedroom and bath by open living area.  User friendly kitchen with plenty of cupboard space and peninsula counter to separate kitchen from living room.  Separate rear entrance combines for mud room and laundry room with washer and dryer.  Small open deck off the main entrance.  Season creek.

    While there are no bells and whistles with this Sagle Idaho 3 bedroom home for sale, it is clean, good bones, ready to move in, and at a price confirming the fact there is a motivated seller.

Share with